The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
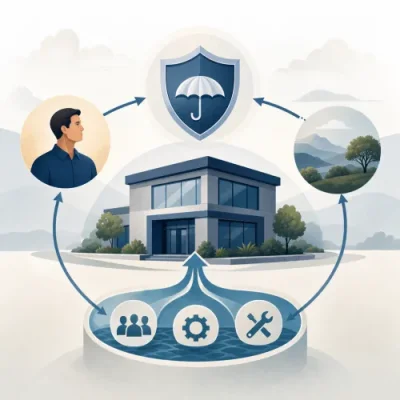
Key person insurance ownership affects who controls the policy, who pays premiums, who receives a payout and how the money may be used if a key person dies or becomes seriously ill. This guide explains common Australian business structures and how they differ from buy-sell and personal life insurance.
Key person insurance can be an important part of business continuity planning, but the way the policy is structured matters. Ownership, beneficiary arrangements and the intended use of any payout can affect who controls the cover, who receives claim proceeds and whether the arrangement supports the business purpose you had in mind.
This article explains, in general terms, how ownership and payouts commonly work for key person insurance in Australia. It is designed for business owners, directors, partners and shareholders who want to understand the structure before comparing policies or speaking with an adviser. For a broader introduction to the product itself, see our practical guide to keyman insurance.
What does policy ownership mean in key person insurance?
The policy owner is the person or entity that legally controls the life insurance policy. In a key person insurance arrangement, the owner may have the ability to pay premiums, update certain policy details, make changes permitted by the insurer, receive notices and, depending on the policy design, receive or direct claim proceeds.
The insured person is different. The insured person is the individual whose death, terminal illness, total and permanent disablement, trauma or another insured event may trigger a claim, depending on the type of cover selected.
A founder, managing director, revenue-generating partner, specialist technician or senior employee could potentially be a key person if their absence would materially affect the business. In many key person insurance arrangements, the business owns the policy and the key person is the insured life. This is not the only possible structure, but it is a common starting point because the business is usually the party exposed to the financial loss.
Policy owner, insured person and beneficiary: the key differences
Key person insurance discussions can become confusing because several roles may be involved. Before choosing a structure, it is useful to separate the following concepts.
| Role |
What it means |
Why it matters |
| Policy owner |
The person or entity that controls the policy. |
Ownership can affect control, notices, policy changes and who may receive or direct claim proceeds. |
| Insured person |
The key individual whose life or health is insured. |
A claim depends on an insured event affecting this person, subject to the policy terms. |
| Beneficiary or payout recipient |
The person or entity intended to receive claim proceeds. |
The payout recipient should align with the purpose of the cover. |
| Premium payer |
The person or entity funding the premiums. |
This is often the policy owner, but not always. It may also be relevant to accounting and tax records. |
Who usually owns a key person insurance policy?
For business-owned key person insurance, the owner is commonly the operating company, partnership entity or other business structure that would suffer if the key person could no longer contribute. The business may also pay the premiums from business funds.
This structure is often used where the purpose of the cover is to protect the business rather than the insured person’s family. For example, the business may want funds to replace lost revenue, recruit a replacement, repay debt, reassure suppliers or maintain operations during a transition period.
Policy ownership should be considered carefully because it can affect control, tax treatment, accounting treatment, claim administration and stakeholder expectations. Ownership should also align with company documents, partnership agreements, shareholder agreements and any loan or funding arrangements.
Where the structure is complex, businesses often speak with an insurance broker, accountant and solicitor before finalising the arrangement.
Who receives the key person insurance payout?
The term “beneficiary” is often used to describe who receives the money if a claim is accepted. In practice, this depends on the policy terms and ownership structure. In a typical business-owned key person policy, the intended recipient of a key person insurance payout is the business or the entity that owns the policy.
This can surprise some business owners because life insurance is often associated with family protection. With key person insurance, the purpose is usually different. The insured person’s family may not automatically receive the payout unless the policy is structured that way or separate personal life insurance is also in place.
The important point is that the policy structure should match the intended purpose. If the business needs the money to manage disruption, repay debt or fund replacement costs, a business-owned arrangement may be considered. If the purpose is family protection, a personal life insurance structure may be more relevant. These purposes should not be assumed to be interchangeable.
How can a key person insurance payout be used?
A key person insurance payout is generally intended to help the business manage the financial impact of losing a critical person. The exact use will depend on the business’s needs, policy purpose, ownership structure, claim circumstances and any agreements between shareholders, partners, lenders or other stakeholders.
Common uses may include:
- Replacing lost revenue where the key person generates sales, manages major clients or drives strategic decisions.
- Funding recruitment and training costs for a replacement or interim manager.
- Helping the business meet debt obligations where the key person was important to profitability or lender confidence.
- Supporting working capital, including wages, supplier payments or other operating costs during disruption.
- Providing reassurance to investors, lenders or suppliers that the business has considered continuity risk.
- Supporting an orderly restructure or closure if the business cannot continue in the same form.
A payout is not a guarantee that a business will recover or continue trading. It is a funding source that may help manage risk, subject to the policy terms, claim assessment and how the business uses the funds.
Why ownership and payout purpose should match
Problems can arise when the policy owner, insured person and intended payout use do not match the commercial purpose of the cover. For example, if the business needs funds to repay a loan but the policy is owned personally, the payout may not automatically be available to the business. Conversely, if the intention is to provide family protection, a business-owned policy may not achieve that purpose.
A clear structure can help avoid misunderstandings between directors, shareholders, partners, employees and family members. It can also make quote discussions more practical because the broker or insurer can better understand what the cover is intended to do.
When discussing key person insurance, consider documenting:
- why the business is taking out the cover;
- who the key person is and why they are financially important;
- who will own the policy;
- who will pay the premiums;
- who is intended to receive any payout;
- how the payout may be used;
- how the arrangement interacts with shareholder, partnership or loan agreements; and
- who will review the policy as the business changes.
Estimating the financial exposure created by the loss of a key person can also help frame the ownership and payout discussion. The Keyman Insurance Calculator may assist with thinking through lost profit, disruption costs and liabilities, although any cover amount should still be considered in the context of the business’s circumstances.
Key person insurance vs buy-sell insurance
Key person insurance and buy-sell insurance are often discussed together, but they usually serve different purposes. A key person policy is commonly designed to protect the business from financial disruption. Buy-sell cover is generally designed to fund the transfer of ownership interests if an owner dies, becomes disabled or suffers another insured event covered by the arrangement.
| Feature |
Key person insurance |
Buy-sell insurance |
Personal life insurance |
| Typical purpose |
Protect the business from financial loss linked to a key person. |
Fund the purchase or transfer of an owner’s equity interest. |
Protect the insured person’s family or personal beneficiaries. |
| Common policy owner |
The business or a related business entity. |
May be owned by business owners, a trust, the company or another structure depending on the agreement. |
The individual insured person or another personal owner. |
| Common payout recipient |
The business. |
The party required to buy or transfer the ownership interest, depending on the structure. |
Personal beneficiaries, estate or nominated recipient. |
| Main use of funds |
Working capital, debt repayment, replacement costs or continuity expenses. |
Ownership succession and equity transfer funding. |
Family living costs, personal debt repayment or estate planning needs. |
| Key document to align with |
Business continuity plan, loan agreements and board or partnership records. |
Buy-sell agreement, shareholder agreement or partnership agreement. |
Estate planning documents and personal financial plan. |
The distinction matters because a keyman insurance versus buy-sell insurance decision is not just about which policy is cheaper or easier to arrange. It is about what problem the cover is meant to solve. Some businesses may need more than one type of planning, but the structure depends on their ownership, cash flow, tax position and legal agreements.
What if the key person is also a business owner?
Many Australian SMEs rely heavily on a founder, director or working shareholder. In that case, the person may be both a key person and an owner of the business. This can create overlapping needs.
For example, the business may need key person insurance to replace revenue or repay debt if the owner can no longer work. At the same time, the other owners may need a buy-sell arrangement to fund the transfer of that person’s shareholding. The owner’s family may also need personal life insurance to meet household expenses or personal debts.
These needs are related, but they are not identical. Using one policy for the wrong purpose can leave a gap. A business owner life insurance discussion should therefore separate business continuity, ownership succession and family protection before deciding who owns each policy and where any payout should go.
Can ownership or beneficiaries be changed later?
Some policy details may be changed after a policy is issued, but changes are subject to the insurer’s rules, the policy terms and any legal or tax consequences. A change in ownership, beneficiary arrangements or policy purpose may also affect tax treatment or business agreements.
Businesses should review ownership and payout arrangements when there are material changes, such as:
- a new shareholder, partner or director joining the business;
- a key person leaving or changing role;
- new debt or investor funding being introduced;
- a restructure, sale or merger;
- changes to revenue reliance or client concentration;
- changes in family or estate planning needs; or
- premium affordability concerns.
It is better to review the structure before a claim event occurs. Once a claim is underway, there may be limited ability to change who receives the money or how the policy is treated.
Tax and accounting considerations
The tax treatment of key person insurance can be complex. It may depend on the policy purpose, whether the cover is for revenue or capital protection, who owns the policy, who pays the premiums, the type of cover and how any payout is used. Accounting treatment can also vary depending on the business and policy structure.
Because tax outcomes are specific to the circumstances, this article does not provide tax advice. Business owners should seek guidance from a qualified tax adviser or accountant before relying on premium deductibility or payout treatment. It may also be useful to keep records showing the commercial purpose of the policy when it is established and reviewed. For more detail on this separate topic, see our guide to key person insurance tax treatment in Australia.
Questions to ask before comparing key person insurance
Before requesting keyman insurance quotes, it can help to clarify the structure you want to explore. Useful questions include:
- Which person is genuinely critical to revenue, operations, lending or business value?
- What financial loss could occur if that person died or could not work?
- Should the business, owners or family receive the payout?
- Is the purpose revenue protection, debt protection, ownership succession or personal protection?
- Who should pay the premiums?
- Do existing shareholder, partnership or loan agreements already specify insurance requirements?
- Would a separate buy-sell or personal policy be needed?
- How often should the cover amount and ownership structure be reviewed?
Once these questions are clearer, comparing options becomes more practical. If you are ready to explore cover, you can start from the Keyman Insurance Australia homepage and request information about quote options. Policy availability, pricing and underwriting outcomes will depend on the insured person’s circumstances, the business details and provider criteria.
Final Thoughts
In a common key person insurance arrangement, the business owns the policy, pays the premiums and receives any payout if a valid claim is accepted. The payout is then used to support the business through disruption, such as replacing revenue, funding recruitment, meeting debt obligations or maintaining working capital.
However, there is no single structure that suits every business. Ownership and beneficiary arrangements should reflect the purpose of the cover and should be coordinated with legal, tax, accounting and succession planning considerations. The most important step is to decide what problem the policy is meant to solve before comparing policies.
Published: Tuesday, 6th Oct 2026
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.